The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
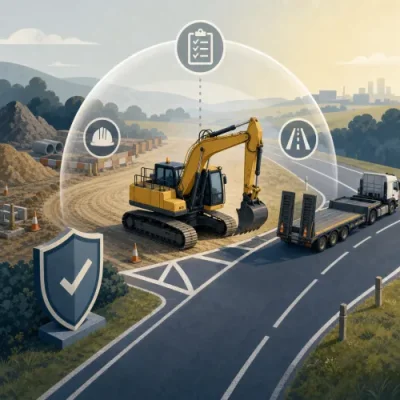
Mobile plant can face different insurance and regulatory issues when it is transported between worksites or operated on or near public roads. Businesses should understand how plant insurance, transit cover, registration, CTP and liability policies may interact.
Why road use changes the insurance conversation
Mobile plant insurance can become more complex when machinery is moved between worksites, loaded onto trailers, driven across public roads or operated near traffic. An excavator, loader, crane, forklift, grader or other item of plant may be well protected while sitting on a secure site, but different risks can arise once it is in transit or interacting with public road users.
For Australian contractors, civil works businesses and earthmoving operators, the key issue is that one policy may not respond to every type of loss. Commercial plant and equipment insurance may help protect the machine itself, but road registration, compulsory third party insurance, public liability, motor insurance and transit cover may also need to be considered depending on how the plant is moved and used.
This article provides general information only. Insurance requirements, registration rules and policy outcomes vary by state or territory, equipment type, business activities and insurer criteria.
Common situations that create extra risk
Mobile plant may be exposed to additional risks when it leaves a controlled worksite. These can include:
- loading and unloading plant onto a float, tilt tray or low loader;
- damage during transport between depots, projects or hire locations;
- theft while equipment is parked offsite or overnight in transit;
- collision while the plant is driven on or across a public road;
- damage to surrounding vehicles, property, road surfaces or underground services;
- injury to road users, pedestrians, workers or bystanders;
- contractual disputes about who is responsible for hired-in or hired-out plant; and
- claims being affected by policy exclusions, road-use conditions or registration status.
The right insurance response depends on what happened, where it happened, who was operating the plant, whether it was being transported or self-propelled, and what each policy actually covers.
Mobile plant insurance is not always the whole answer
Plant and equipment insurance is generally designed to protect the insured item against physical loss or damage, subject to the policy wording. It may cover events such as accidental damage, fire, theft, malicious damage or certain site risks. Some policies may include or offer additional cover for transit, wet hire, dry hire, attachments, tools or recovery costs, but this should not be assumed.
When mobile plant is used on public roads or moved between sites, other insurance categories may become relevant. The distinction between damage to your machine and damage or injury caused to someone else is particularly important. For a broader explanation of that difference, see general liability insurance versus plant and equipment insurance.
| Insurance or requirement |
What it may relate to |
Important limitation to check |
| Plant and equipment insurance |
Physical loss or damage to the insured machine |
Road use, transit, attachments, theft conditions and exclusions may vary |
| Transit or goods-in-transit cover |
Loss or damage while equipment is being transported |
Loading, unloading, securing, subcontracted transport and unattended vehicle conditions may be treated differently |
| Motor or road risk cover |
Use of registered or road-operated plant on public roads |
Not all plant policies automatically cover road-related collisions or third-party property damage |
| CTP insurance |
Compulsory injury cover linked to registered vehicles in Australian jurisdictions |
CTP does not usually cover damage to the plant itself or third-party property damage |
| Public or general liability insurance |
Third-party injury or property damage arising from business operations |
Motor vehicle, road use, professional, contractual or pollution exclusions may apply |
| Hired plant insurance |
Owned, hired-in or hired-out plant depending on the arrangement |
Hire agreements may shift responsibility for damage, loss, excesses or downtime |
Road registration, permits and CTP for mobile plant
Some mobile plant may need road registration, conditional registration, permits or other approvals before it can be operated on public roads or road-related areas. Requirements differ between Australian states and territories, and they may depend on the machine type, size, speed, use, route and whether it is self-propelled or transported.
Compulsory third party insurance, commonly called CTP, is generally linked to registered vehicles and is intended to respond to certain personal injury claims involving the use of the vehicle. However, CTP should not be treated as a replacement for mobile plant insurance, public liability insurance or third-party property damage cover.
For example, if a road-registered item of mobile plant is involved in an incident, CTP may be relevant to injury claims depending on the circumstances and jurisdiction. It would not normally pay to repair your own machine, replace stolen attachments or cover damage to another vehicle or fence. Those issues may sit under separate plant, motor, property damage or liability covers, if insured.
Transit risks when moving plant between worksites
Moving plant between sites can create a separate risk profile from operating it. Damage may occur while machinery is being loaded, chained down, transported, unloaded or temporarily stored. A policy may distinguish between damage while the plant is operating, damage while it is being carried, and damage caused by inadequate securing or transport arrangements.
Businesses should check whether their plant equipment transit insurance arrangements address:
- whether cover applies while the plant is on a trailer, float, truck or low loader;
- whether loading and unloading are included or excluded;
- whether transport by an employee is treated differently from transport by a subcontractor;
- whether the plant must be secured in a particular way;
- whether overnight parking or unattended transport stops are covered;
- whether attachments, buckets, tools, GPS equipment and accessories are listed; and
- what excesses, limits and claim evidence requirements apply.
If a third-party transport operator is used, their insurance may not fully protect your financial interest in the machine. Their liability may be limited by contract, law or the terms of their own policy. It is sensible to understand both your cover and the carrier's responsibilities before equipment is moved.
Using mobile plant on or near public roads
Roadside and roadworks environments can involve mixed risks: machinery damage, public liability, traffic management, worker safety and compliance with road authority or client requirements. Plant may not need to travel far to create a road-related exposure. Crossing a public road, operating partly on a road shoulder, unloading on a nature strip or manoeuvring near live traffic can all raise questions about cover.
Insurance issues to consider include:
- where the incident occurred: on a private site, public road, road reserve, footpath, shared access area or client-controlled project;
- how the plant was being used: working, travelling, loading, unloading, parked or being towed;
- who was operating it: employee, subcontractor, labour hire worker, hirer or transport contractor;
- whether the plant was road registered: and whether any registration conditions were followed;
- whether traffic management was required: including permits, spotters, signage or exclusion zones; and
- whether the policy excludes road use: some policies may contain motor vehicle, unregistered vehicle or public road exclusions.
These details can affect which policy responds, whether more than one policy is involved, and whether an insurer applies exclusions or conditions.
Owned, hired-in and hired-out plant
Responsibility can become more complicated when equipment is hired. A dry hire arrangement may place operational control and damage responsibility on the hirer. A wet hire arrangement may involve the owner's operator and different liability assumptions. Hire contracts often set out who must insure the plant, who pays the excess, and who is responsible for damage, theft, downtime or recovery costs.
Before moving hired plant between sites or using it near public roads, businesses should review:
- the hire agreement's insurance clauses;
- whether road use is permitted under the hire terms;
- whether the plant can be transported by the hirer or only by an approved carrier;
- whether the machine must be listed on the hirer's policy;
- whether damage during loading or unloading is covered;
- whether loss of hire charges or continuing hire fees are insured; and
- what evidence is needed if a claim occurs.
Contract terms and insurance policy terms are separate documents. A contract may require you to accept responsibility for a loss that your insurance does not automatically cover.
Questions to ask before mobile plant is moved or road-operated
Because requirements vary by equipment type, use and location, many businesses discuss their circumstances with an insurer or broker before relying on an existing policy. You can use the site's broker information as a starting point if you need help identifying questions to ask.
Useful questions include:
- Is this item of plant specifically listed on the policy, including attachments and accessories?
- Does the policy cover transit between worksites?
- Are loading and unloading covered?
- Does cover apply if the plant is transported by a subcontractor?
- Is road use covered, excluded or subject to conditions?
- Does the plant need registration, conditional registration, permits or CTP?
- Is third-party property damage covered if the plant hits a vehicle, building, service or road asset?
- Are there exclusions for unlicensed operators, unregistered plant or non-compliant use?
- Do contracts with principals, councils, builders or hire companies require specific insurance limits?
- What documents would be needed to support a claim?
Records that can support compliance and claims
Good records can help a business demonstrate ownership, value, maintenance, risk management and the circumstances of a loss. They may also help clarify responsibility when multiple parties are involved.
Depending on the equipment and work, useful records may include:
- asset registers with serial numbers, make, model and attachments;
- purchase invoices, hire agreements or finance documents;
- service, inspection and maintenance records;
- operator licences, competency records or induction documents where relevant;
- transport dockets, delivery records and carrier details;
- photos of plant condition before and after transport;
- traffic management plans or permits for roadworks environments;
- registration, conditional registration or permit documents; and
- incident reports, witness details and repair assessments.
Insurers may have specific notification and evidence requirements. Delays in reporting an incident, unauthorised repairs or missing information can complicate the claims process.
Bringing the cover together
Mobile plant used on roads or moved between worksites can sit at the intersection of several insurance and compliance areas. Plant insurance may protect the machine, transit cover may address movement between locations, CTP may be relevant to certain injury claims involving registered plant, and liability insurance may respond to some third-party injury or property damage claims.
The important point is not to assume that one policy covers every scenario. Businesses should review how each item of plant is used, how it is transported, whether it enters public roads or road-related areas, and what contracts or regulators require. Policy wording, exclusions, registration status and individual circumstances will determine how cover may apply.
Published: Wednesday, 19th Aug 2026
Author: Paige Estritori


No comments yet. Be the first to share your thoughts.