Plant And Equipment Insurance Online Plant & Equipment Lease Calculator
Estimate repayments with our Plant & Equipment Lease Calculator. Factor in residual (balloon) payments, compare finance options, and choose flexible terms to suit your business.
Calculator results are estimates only and not quotes. Actual quotes will be provided by licensed brokers after you submit an enquiry.
Business Asset Lease Details:
Important!
Business Asset Lease Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.). To find out if you qualify ... and for a free, personalised interest rate and repayment quote, please CLICK HERE
Business Asset Lease Amortisation Calculator
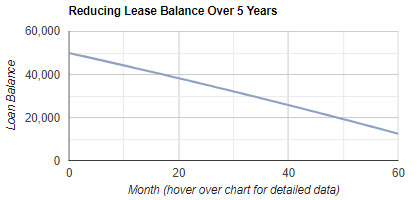
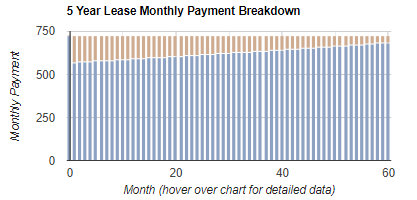
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Plant & Equipment Lease Calculator
Our Plant & Equipment Lease Calculator helps business owners estimate lease repayments before you speak with a lender. It’s important because changing the residual (balloon), term and interest rate can materially affect cash flow, total interest paid and the end-of-term payout amount. The calculator provides estimates only and is general information, not personal advice; consider your objectives, financial situation and needs, and check the lease contract, fees and tax treatment with your accountant or adviser.
How to complete the calculator (best-practice order):
1. Purchase Price: Enter the total amount you want to finance, using whole numbers only (no dots or commas). Include relevant on-road and acquisition costs you intend to finance, such as applicable tax, stamp duty, registration, insurance or other costs.
2. Balloon or Residual Value: Choose the residual as a percentage of the purchase price. A higher residual usually lowers the ongoing repayments, but increases the amount due at the end and can increase the overall cost across the term. Select a residual that matches your expected end-of-term plan (refinance, trade-in, or pay out).
3. Term of Loan: Select the number of years. Longer terms typically reduce repayments but can increase total interest paid. Use a term that aligns with the asset’s useful life and how long you expect to keep it.
4. Interest Rate: Select a rate to simulate. The displayed range is indicative only; your actual rate depends on the lender and your circumstances and can only be confirmed after you apply.
5. Calculate: Run the estimate, then re-run scenarios to compare different residuals, terms and rates for a clearer view of affordability versus total cost.
How to interpret the results:
1. Repayment estimate: Treat this as a guide for budgeting, not a quote.
2. Residual due: Note the end-of-term balloon amount you’ll need to pay or refinance.
3. Amortisation graphs: Review how the balance reduces over time and how each repayment splits between interest and principal, which helps you understand cost versus payoff progress.
Australia's construction sector remains under pressure, with recent insolvency figures continuing to show building and construction as one of the most exposed parts of the economy. Higher material costs, tight margins, labour shortages, delayed payments and fixed-price contract stress have all contributed to a tougher operating environment for builders, subcontractors and project owners. - read more
Recent transport industry sales updates point to a more selective new-truck market, with operators weighing replacement timing against finance costs, emissions planning, availability and contract confidence. For truck businesses, that matters well beyond the showroom. A change in buying momentum can flow through to vehicle values, repair economics, insurer appetite and the way fleets should set insurance sums before renewal. - read more
Fresh small business cyber warnings are a practical reminder that digital risk is no longer just a concern for large companies with complex IT systems. For Australian tradespeople, the most damaging cyber incident may be far simpler: a fake invoice, altered bank details, a compromised email account or a scam message that looks like it came from a supplier, builder, real estate agent or client. - read more
ASIC’s continuing focus on superannuation member services has put another practical issue in front of Australian workers: insurance inside super is not just about whether cover exists, but whether members can understand and use it when they need help. Recent regulatory attention on trustee administration, communication and claims support is a timely reminder for anyone relying on salary continuance or income protection benefits through their fund. - read more
Recent transport industry reporting has again highlighted growing interest in Performance Based Standards vehicles and other high-productivity truck combinations across Australia. For operators, the attraction is clear: fewer trips, better payload efficiency and stronger productivity on approved routes. For insurers, however, the shift is not simply a matter of adding another truck to the schedule. PBS combinations can alter exposure across vehicle value, route compliance, load responsibility, driver capability and recovery after an incident. - read more
Hiring plant or equipment can help Australian contractors stay flexible, but insurance responsibilities are not always straightforward. This guide explains how dry hire, wet hire, hired-in plant cover, damage waivers and hire agreement terms can affect who is responsible for loss, damage, theft, liability and downtime. - read more
Plant and equipment insurance claims generally involve securing the site, gathering evidence, notifying the insurer, assessing the loss and agreeing on repair, replacement or settlement options. The exact process depends on the policy wording, the insured event and the insurer's claims criteria. - read more
Plant and equipment insurance is a specialized type of coverage designed to protect your crucial assets. This insurance typically covers machinery, tools, and various equipment used in the operations of your business. It ensures that, in the event of damage or theft, you won’t face major financial setbacks. - read more
Plant and equipment insurance is a specialized type of coverage designed to protect construction and contracting businesses against financial losses related to their machinery and tools. This includes any equipment used in the delivery of services, such as excavators, cranes, and other vital equipment. In essence, this insurance safeguards your investment, providing peace of mind as you focus on your projects. - read more
Mobile plant can face different insurance and regulatory issues when it is transported between worksites or operated on or near public roads. Businesses should understand how plant insurance, transit cover, registration, CTP and liability policies may interact. - read more
Knowledgebase
Underwriting: The process by which an insurer determines the risk of insuring a client and decides the terms of coverage.